London’s Future: The Global Stage for Flagship Retail
Prime retail low vacancy highlights flagship demand
Across global cities, there is limited vacancy on prime retail flagship streets, particularly for mid-to-large flagship formats.
This reflects these destinations’ desirability and confidence, with retailers often competing for the best units, and in some cases, offering key money to secure the site. Retailers are clustering to take advantage of high foot traffic and shared customers. For landlords and investors, this tight availability supports rental growth and de-risks income, reaffirming these destinations as durable global stages for brand investment.
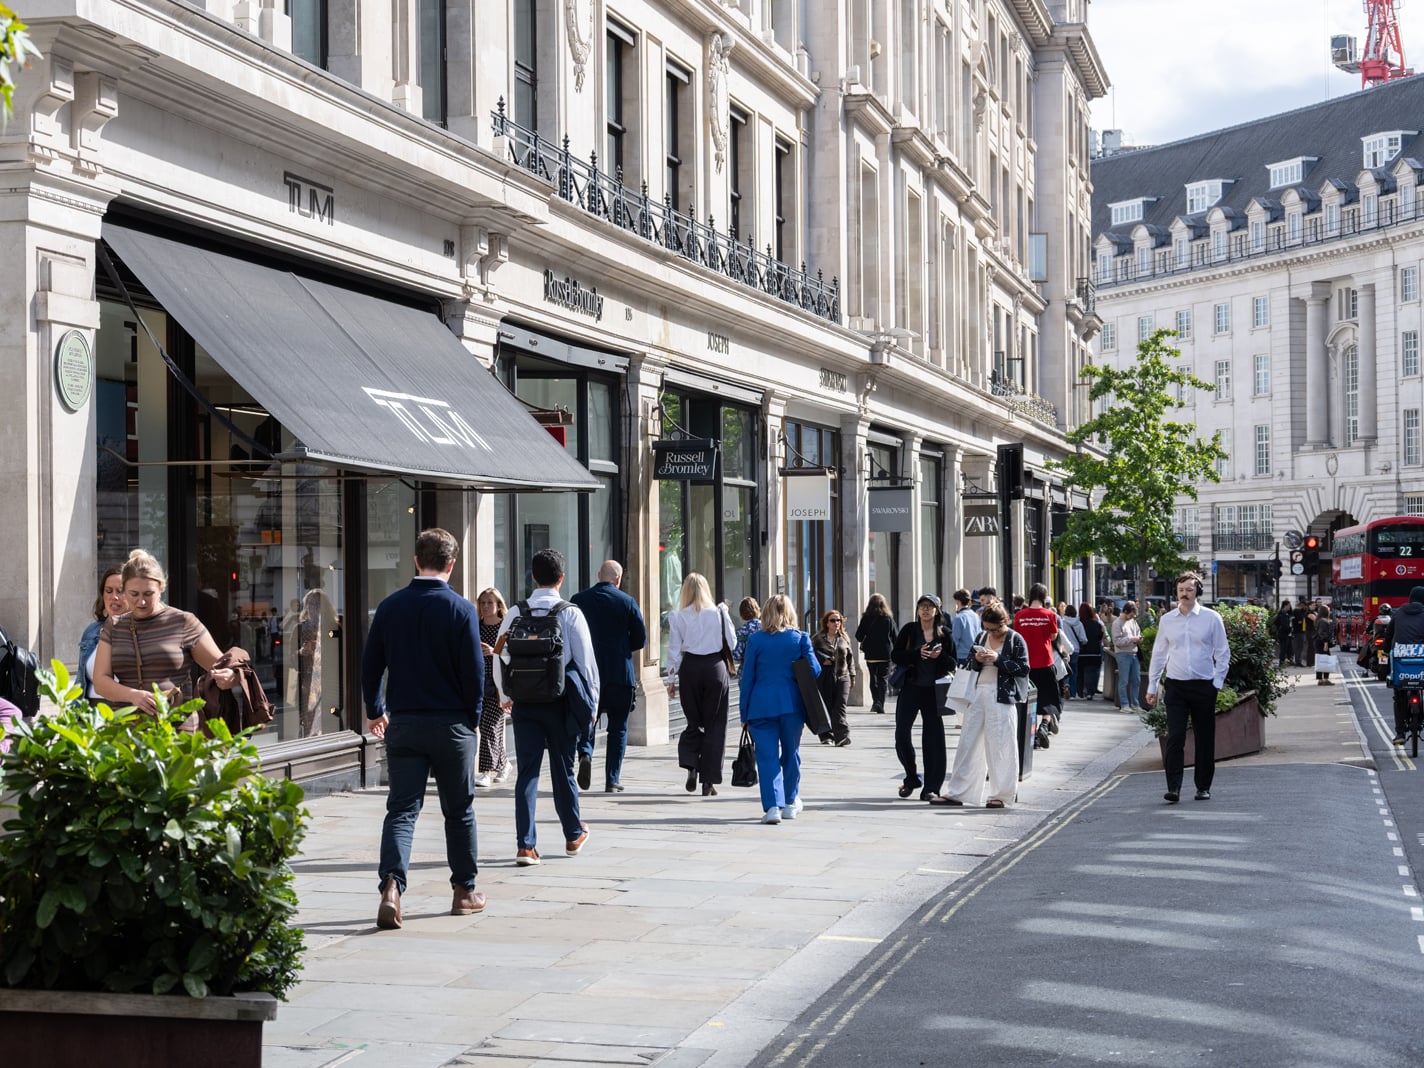
In London, the majority of prime central London streets we track have a sub-4% vacancy rate. Oxford Street vacancy peaked during the pandemic, with large vacant sites eroding the street’s visual appeal. This has significantly shifted, with the latest vacancy rate (H1 2026) at just 0.4% following retailers committing to the street.
Transformation on Oxford Street has also been driven by former department stores, House of Fraser (now Elephant) and Debenhams (now M Building) being redeveloped into mixed-use, office-led schemes with upgraded retail space. They have secured large office occupiers, General Atlantic and BDO, respectively. A similar department-store-turned-mixed-use scheme is on New Bond Street where Lazari is developing the former Fenwick. The 115,000 sq ft entire office space has been let to McDermott Will & Schulte. These schemes will boost footfall and spend in the immediate area, while creating flagship retail opportunities better aligned with current retailer demand. Furthermore, Oxford Street’s proposed pedestrianisation has been welcomed by many retailers due to improving the streetscape to become a more experience-led environment.
Figure 7: City prime locations vacancy rate, H1 2026
In Tokyo, street-level retail supply is extremely tight with brands competing for core locations to open prominent flagships. Ginza is dominated by luxury brands and demand is becoming increasingly diverse in sector and nationality, with Asian retailers showing strong appetite for flagships.
In Paris, demand is highly concentrated in a limited number of established retail locations, such as the Champs-Élysées / the Golden Triangle, Saint-Honoré, Saint-Germain-desPrés (Left Bank) and, increasingly, Le Marais, which has a more trend-driven positioning. However, this demand is facing significant supply constraints, particularly for mid-to-large flagship formats (300–500 m²) that cater to more immersive store experiences.
In Dubai, demand for prime retail spaces, particularly in Super-Regional destination malls like Dubai Mall and Mall of the Emirates, continues to outstrip supply, with vacancy rates at less than 1%. This has been boosted by the growing affluent domestic and tourism population. However, there are sizable expansion plans to extend the floorspace of both centres by 2028.
While low vacancy is positive, limited supply means that it can be challenging for retailers to find space and there is increased affordability pressure when leases expire. Many large brands with financial capacity may wait until the perfect site is available while smaller, emerging brands that are more cost-conscious may opt for adjacent off-pitch locations close to prime areas, where there are more opportunities and rental growth has not been as strong.
Read the next chapter: What’s becoming important for flagships
Continue reading to see how experience, technology and design are reshaping what brands expect from a flagship.
Read the next chapter: What’s becoming important for flagshipsWant to download the full report?
Business Contacts
Richard Smart
Managing Director, Head of London Markets

Phil Cann
Executive Director, Head of London Retail Investment

Peter Flint
Senior Director, Central London Retail


Research Contacts


Related Services
- Property Type
Retail
Delivering solutions to retailers, investors, owners, and developers. Our scale and coverage allow us to provide insight to all retail challenges.
- Retail
Central London Retail
Specialising in Central London retail, our team can help you maximise your retail portfolio through insightful and effective strategies.
- Retail
Retail Investment
Maximising the value of your property assets with our client-centred approach, providing unrivalled retail investment advice across global markets.
- Retail
Occupier Retail Services
Catering for properties and developments of all sizes, advising you on high street, shopping centres and supermarkets.
We’re perfectly placed to provide strategic advice on your cross-border retail and transaction services.
Providing market leading leasing and lease advisory services, ensuring your retail portfolio is working at maximum capacity.
- Retail
Out of Town Retail
We deliver market leading services throughout the UK for domestic and international clients, on retail parks, solus retail warehousing and foodstores.
Providing data driven insights for retail property owners at every stage of the asset life cycle.
- Valuation & Advisory Services
Retail Valuation Services
We have the industry's largest specialist Valuation team, providing unrivaled experience in valuing each retail sector.

Find Retail Property for Sale or Lease

Discover unique commercial retail properties across the UK. A portfolio of former branch properties are now available.

Easily find out-of-town retail properties available to rent in the UK with CBRE, the nation's largest commercial property solution provider.